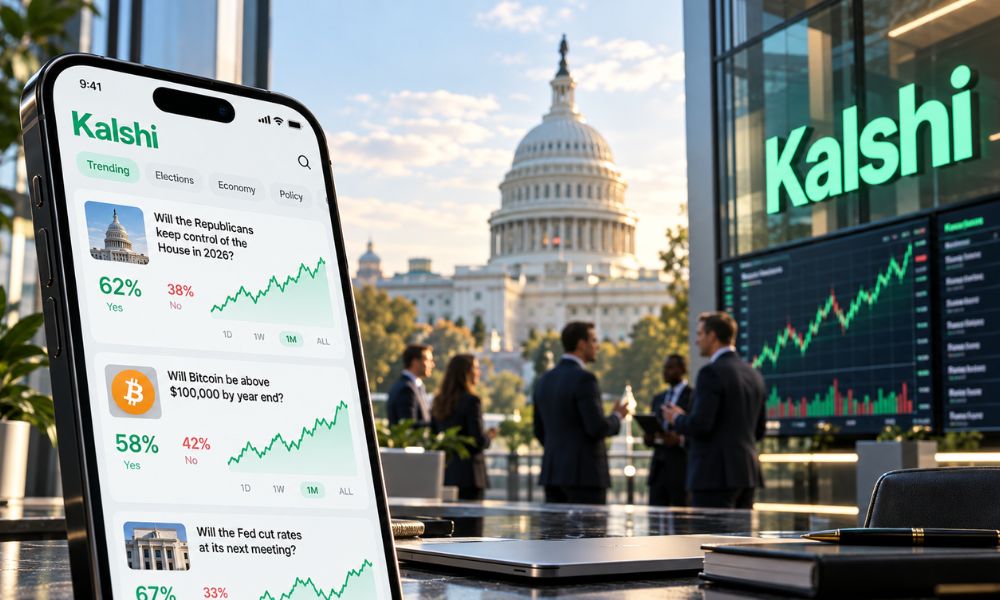
Kalshi has found a valuable group of customers traditional sportsbooks cannot legally serve: Americans aged 18 to 20 and sports fans living in states where conventional online sports betting remains prohibited.
The prediction market allows eligible adults to trade contracts on sporting events under federal commodities regulation. That creates an opportunity in places such as California and Texas, where companies like DraftKings and FanDuel cannot offer traditional online sportsbooks.
The age difference is just as significant. According to Kalshi’s account requirements, users can register at 18, compared with the minimum age of 21 in most states that permit sports wagering.
For Kalshi, that’s a commercial advantage. For state regulators, it’s a challenge to gambling restrictions they have spent years developing.
The more interesting question is whether Kalshi has discovered a genuinely different financial market or simply found a way to reach gambling customers its competitors are legally required to turn away.
The distinction could determine how much of its business survives the next round of court decisions.
Kalshi’s Advantage Starts Where Sports Betting Is Restricted
Traditional sportsbooks operate under state gambling licenses. Their ability to accept customers depends on where those customers are physically located, their ages, and what kinds of wagers state regulators permit.
Kalshi operates differently.
Its contracts trade on an exchange regulated by the Commodity Futures Trading Commission (CFTC). Customers take positions on outcomes, including which team will win a game.
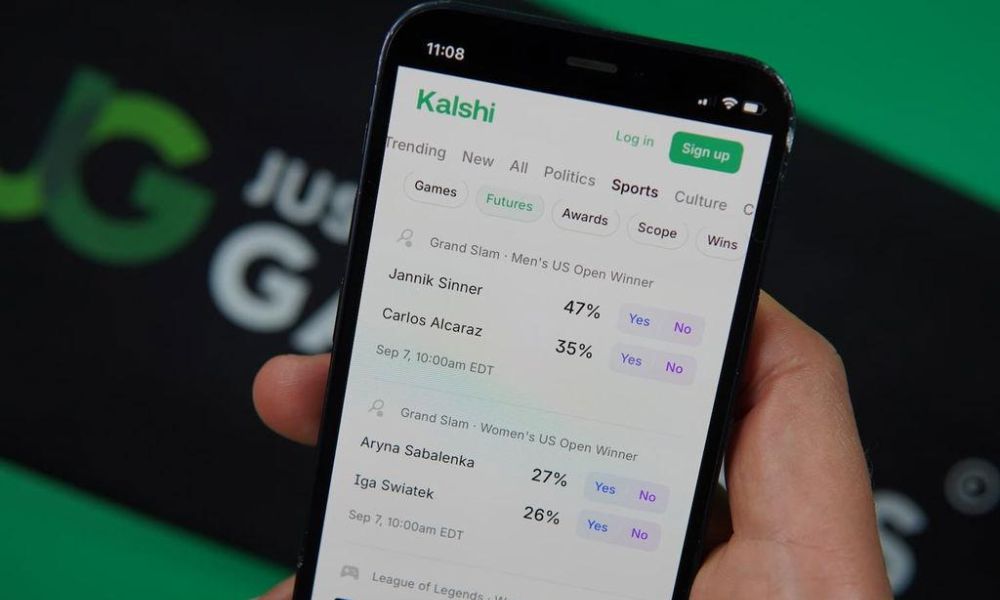
A simplified example explains the mechanics. Suppose a contract predicting a particular team will win costs 40 cents.
- If the team wins, the contract settles at $1.
- If the team loses, it settles at zero.
- The buyer’s potential profit is 60 cents per contract before fees.
- The entire 40-cent investment is at risk.
Kalshi describes these transactions as financial derivatives rather than sportsbook wagers. Its exchange structure also differs from a bookmaker setting odds and taking the other side of customers’ bets.
Yet the customer’s underlying decision looks familiar. Someone believes a team will win and puts money behind that belief.
The economic difference between trading a sports outcome and betting on it is considerably smaller than the legal argument suggests.
That creates an unusually attractive opportunity for Kalshi. It can compete for customers who have no access to conventional online sportsbooks, provided the relevant contracts remain available and legally permissible in their jurisdictions.
Two Groups of Customers Give Kalshi an Opening
The opportunity is easier to understand when we separate customers who cannot use sportsbooks from those who already can.
| Customer Group | Traditional Sportsbooks | Kalshi’s Opportunity |
|---|---|---|
| Adults aged 18–20 | Excluded in most legal sports betting states | Can qualify for an account at 18 |
| Adults in states without legal online sports betting | No licensed online sportsbook available | Can access eligible contracts where Kalshi operates |
| Adults aged 21+ in legal betting states | Can use licensed sportsbooks | Can compare prices and trade with a different provider |
The 18-to-20-Year-Old Audience
A three-year difference in eligibility creates a customer acquisition opportunity.
Someone who begins using Kalshi at 18 could establish trading habits, become familiar with its interface, and develop a preference for its markets before becoming eligible for a conventional sportsbook. That relationship has potential long-term value.
Financial companies understand how important early customer relationships can be. Banks compete for college students. Brokerages offer beginner-friendly investing apps. Payment companies want to become someone’s default way to move money.
Kalshi has a comparable opportunity in sports-related trading. Of course, there’s an important limitation. Kalshi has not publicly established how many of its sports customers are aged 18 to 20, or how much of its growth comes from that demographic.
The opportunity is obvious. Its actual contribution to revenue is much harder to measure.
States Where Online Sportsbooks Cannot Operate
California and Texas are particularly interesting because they have enormous populations, major professional sports teams, and no legal conventional online sportsbooks.
Kalshi can reach eligible customers there through sports event contracts, although legal challenges elsewhere demonstrate that federal registration does not guarantee unrestricted access. This is the larger competitive threat to sportsbooks.
The traditional betting industry has spent years lobbying for state-level legalization. Kalshi has built a business using a regulatory structure that potentially gives it access without waiting for those legislative victories.
Whether that structure holds up in court is another matter.
Sports Trading Has Become a Massive Business
The industry’s growth provides some perspective on why the legal fight has become so intense.
A Pew Research Center analysis published September 23, 2026, found that combined monthly trading volume on Kalshi and Polymarket more than doubled between May and July.
| Month | Combined Monthly Trading Volume |
|---|---|
| May 2026 | $25.7 billion |
| June 2026 | $47.7 billion |
| July 2026 | $53 billion |
Sports became the largest trading category on both platforms. During June and July, sports trading exceeded $58 billion on Kalshi alone.
The figures demonstrate real activity. They do not tell us how profitable that activity is.
Trading Volume Is Not Revenue
Kalshi’s trading numbers require careful interpretation. Pew’s analysis uses notional volume, counting each traded contract at its full $1 payout value rather than necessarily the amount a customer paid.
A contract purchased for 20 cents can therefore contribute $1 to the reported figure. Repeated trading also increases volume without necessarily adding new customers.
That matters when evaluating Kalshi as a business. A company with growing trading volume still needs sufficient fee income to cover technology, compliance, marketing, staffing, and other expenses.
The numbers worth checking are active paying customers, average fees collected per customer, customer acquisition costs, and retention.
A record trading month is impressive. A profitable and loyal customer base would tell us considerably more.
Kalshi’s Biggest Risk Is Its Regulatory Advantage
The same legal structure that gives Kalshi access to these customers now threatens its business.
The central disagreement is straightforward. Kalshi argues that federally regulated event contracts fall under CFTC jurisdiction. State gambling regulators argue that sports contracts function as sports betting and must comply with state gambling laws.
Federal courts have reached conflicting conclusions.
The debate over whether Kalshi’s sports contracts should be treated as financial trading or traditional sports betting has also attracted attention from local news outlets. The following WFSB Channel 3 report examines that distinction and the legal questions surrounding the platform.
In August 2026, the Ninth Circuit ruled against Kalshi in its dispute with Nevada. On September 25, the Sixth Circuit ruled that Ohio and Tennessee could apply their gambling laws to Kalshi’s sports contracts. The Third Circuit previously sided with Kalshi in a New Jersey dispute.
The dispute has now reached the doorstep of the Supreme Court.
On October 8, the NFL supported New Jersey’s request for Supreme Court review. According to Reuters’ reporting on the filing, the league also wants stronger protections against insider activity, restrictions on manipulation-sensitive wagers, and a minimum trading age of 21.
Kalshi has until November 9 to respond to the petition, with a decision on whether the Supreme Court will hear the case not expected before December.
For Kalshi, a nationwide 21-year minimum would eliminate one of its most obvious advantages. Applying state sportsbook rules to sports contracts could be even more consequential.
There’s a business lesson here. Regulatory advantages can create exceptional growth, but they’re difficult to value when courts haven’t settled whether the underlying model is permissible.
The Consumer Protection Question Deserves More Attention
The argument that placing a sports wager through an exchange automatically makes it a more sophisticated financial activity deserves closer scrutiny.
The interface changes. The economic risk of losing money on an uncertain sporting outcome remains.
In our previous article on Gen Z investors and sports betting, we examined a Betterment survey showing that 52% of Gen Z investors surveyed had redirected money originally intended for investing toward sports betting.
That does not establish that those investors used Kalshi. It does show why the distinction between investment products and sports speculation deserves scrutiny.
Kalshi has identity verification, market surveillance, and trading rules. It is not operating without federal oversight. The CFTC’s proposed regulatory framework, announced in June, also addresses event contracts involving activities such as gaming.
Still, a customer losing money repeatedly on sports predictions faces a financial problem regardless of which regulator supervises the platform.
Calling the activity trading doesn’t change the losses.
What I Would Watch Next
Kalshi’s future depends on more than how many contracts change hands. Three developments matter most.
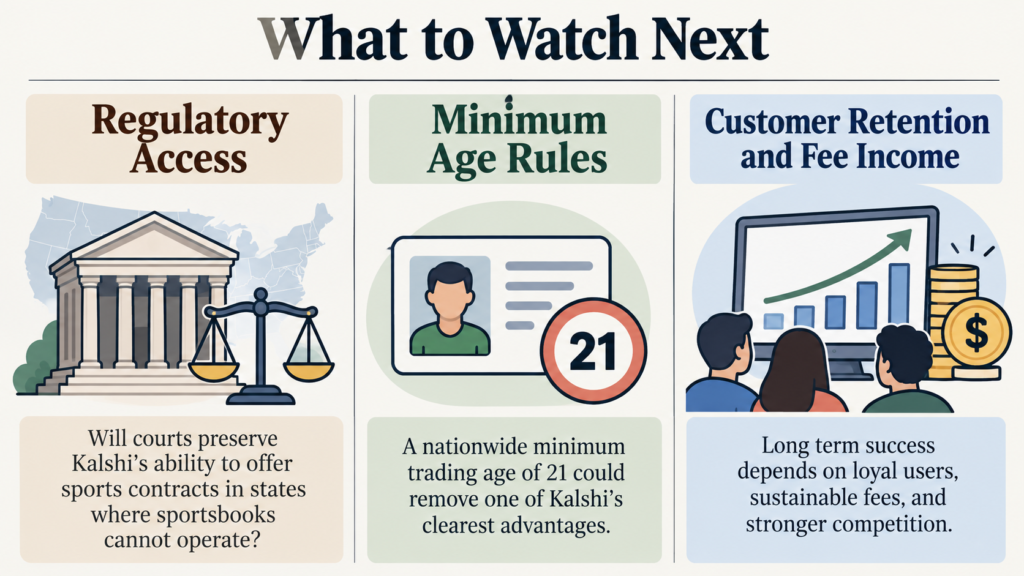
First is whether courts preserve its ability to offer sports contracts in states where sportsbooks cannot operate. Second is whether regulators impose a minimum trading age of 21.
Third is whether Kalshi can retain customers and generate sustainable fee income as competition increases. I also think there’s a longer-term customer loyalty question.
If California or Texas eventually legalizes conventional online sportsbooks, Kalshi could enter that newly competitive market with an established base of customers. Acquiring those relationships early would have been valuable.
Yet the same customers could switch providers if sportsbooks offer better prices, promotions, or products.
Kalshi has identified demand that the traditional betting industry cannot fully serve under its current rules. That’s commercially significant.
The unanswered question is how much of that advantage belongs to Kalshi’s product, and how much exists because its competitors have to follow different laws.
The company’s trading growth proves that people want access. The next phase will determine whether Kalshi can turn that demand into a durable business once the regulatory boundaries are settled.