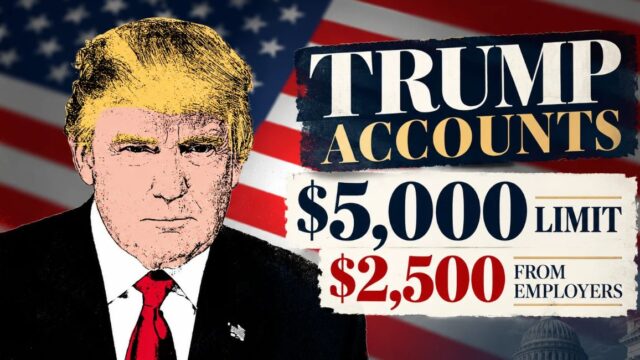
American employers can now contribute up to $2,500 a year to an employee’s child’s Trump Account without the contribution counting toward the employee’s federal taxable income.
For parents, that’s an attractive benefit. An extra $2,500 invested early in a child’s life could grow considerably before the child reaches adulthood.
There’s just one problem. Most employers don’t seem particularly interested.
A September 2026 survey by the Plan Sponsor Council of America (PSCA) found that 72% of responding employers were neither contributing to Trump Accounts nor interested in doing so. Just 1.3% were already making contributions.
That gap between what the law allows and what employers actually want to do is more interesting than the $2,500 figure itself.
The government has created another way for companies to help employees build family wealth. Whether companies see enough value in offering it is a different question.
How the $2,500 Employer Contribution Works
Trump Accounts were created under the One Big Beautiful Bill Act, signed into law in July 2025. They are tax-advantaged investment accounts designed to help children build savings through long-term stock market investments.
Contributions began on July 4, 2026, and the IRS issued proposed employer contribution regulations on August 11.
The rules allow employers to contribute up to $2,500 annually to Trump Accounts belonging to employees or their dependents.
There are a few details worth understanding.
Second, employer contributions count toward the general $5,000 annual contribution limit for each account.
Employer contributions are just one way to fund a Trump Account. Wealth and Estate Law Group explains who else can contribute, including family members, and how the annual contribution limits apply.
Third, the income tax advantage doesn’t eliminate payroll taxes. According to the IRS, qualifying employer contributions remain subject to Social Security and Medicare taxes.
Employers can also let workers direct some of their own pretax salary into dependent children’s accounts. That’s useful, but it’s different from a company providing additional money.
A contribution funded through salary reduction is still coming out of the employee’s compensation.
That’s an important distinction when evaluating how generous this benefit really is.
The Numbers Show Very Little Employer Interest
Most Employers Aren’t Interested in Trump Accounts
Employer responses to the September 2026 PSCA survey
72%
19%
8%
1.3%
Source:
Plan Sponsor Council of America (PSCA), September 2026
.
Figures are rounded and may not total exactly 100%.
The PSCA’s September survey paints a fairly discouraging picture for anyone expecting Trump Account contributions to become a standard workplace benefit.
Only two employers responding to the survey were already contributing.
These figures come from a PSCA employer poll, not a nationally representative survey of every American business. They shouldn’t be interpreted as exact adoption rates across the entire economy. Still, the direction is difficult to ignore.
An earlier Mercer survey conducted in February 2026 found that nearly 16% of respondents were planning or considering Trump Account funding options, including employee-funded arrangements.
The September findings suggest that having the program operational and receiving additional regulatory guidance hasn’t suddenly made employers enthusiastic. And the reasons are understandable.
Employers Have a Fairness Problem
The most interesting finding in the PSCA survey wasn’t a percentage. It was the reason employers gave for avoiding the program. Fairness was the most common concern.
Imagine a company with 100 employees. Some have young children. Others have adult children, and some don’t have children at all.
If the company starts contributing $2,500 annually to eligible children’s accounts, the benefit won’t reach everyone.
An employee with two young children might receive a valuable addition to their compensation package. Someone doing the same job without eligible dependents receives nothing.
Employers already offer family-specific benefits, of course. Health insurance, parental leave, and dependent care assistance don’t benefit everyone equally.
But adding another benefit that reaches only part of the workforce raises a reasonable question: Is this the best use of the company’s compensation budget? There’s also the cost.
If 200 employees receive a $2,500 employer contribution, that’s $500,000 annually before administration costs.
For a profitable large corporation, that might be manageable. For a smaller business, it’s a serious commitment.
Companies must also establish written programs, handle account verification, manage reporting, and satisfy nondiscrimination requirements.
A new employee benefit sounds simple until someone in payroll has to administer it.
For business owners considering this benefit, tax professional Kristin Gunderson explains how the $2,500 employer contribution works, including the tax advantages and administrative requirements companies need to consider.
Some Major Companies Are Moving Anyway
Not every employer is staying on the sidelines.
Financial technology company Chime announced a $1,000 match for employees’ children eligible for the federal seed contribution. It later expanded its commitment with $250 contributions for other employees’ children with Trump Accounts.
Strategy announced plans to contribute $250 annually for every eligible child under 18 of its U.S. employees, plus a one-time $1,000 contribution for qualifying newborns.
These announcements are encouraging, although announced commitments and completed contributions aren’t necessarily the same thing. They also highlight a familiar pattern in employee benefits.
Large, financially secure companies can afford to experiment with new perks. Smaller employers are more likely to stick with benefits they know employees value.
You shouldn’t be surprised if Trump Account contributions eventually become another advantage concentrated among workers who already have relatively generous benefit packages.
That would be an unfortunate outcome for a program intended to broaden access to wealth building.
The Money Could Make a Real Difference
Despite the weak employer interest, the basic idea of putting investment money to work early in a child’s life is solid.
Consider a single $2,500 contribution made when a child is born. At an illustrative 6% annual return, that contribution would grow to approximately $7,100 over 18 years, before taxes and inflation.
For a longer-term perspective, see what a $1,000 Trump Account could be worth by retirement and how decades of investment growth can affect a child’s savings.
That’s not a forecast. Stock market returns fluctuate, and the investment could lose value. But the calculation demonstrates why early contributions matter.
Eligible U.S. citizen children born from 2025 through 2028 can also receive a one-time $1,000 federal contribution. That government payment doesn’t count toward the ordinary $5,000 annual limit.
What is concerning is that families who can afford to contribute regularly, especially those receiving employer money, could accumulate substantially more than families relying entirely on the initial government deposit.
The investment opportunity is broadly available. The ability to fund it isn’t.
What Parents Should Do Now
The first thing we’d suggest is checking whether your employer offers a Trump Account contribution program or plans to introduce one.
Ask human resources whether the company provides direct contributions, employee-funded pretax contributions, or neither. Don’t assume an advertised $2,500 limit means your employer will actually provide $2,500.
Morton Financial Advice also takes a closer look at employer contributions to Trump Accounts, explaining how the benefit works and what families should consider before taking advantage of it.
Parents should also claim their children’s accounts. Following automatic enrollment in October 2026, the Treasury Department said eligible children’s accounts must be claimed by a parent or guardian before employers or family members can contribute.
Claims can be completed through the official Trump Accounts app.
And remember that this isn’t an ordinary savings account. Investments generally remain locked until the calendar year the child turns 18. After that, traditional IRA withdrawal rules apply, potentially including income taxes and early withdrawal penalties.
For families saving specifically for education, an existing 529 plan may still offer better tax treatment for qualified expenses.
The Real Test Isn’t the $2,500 Limit
The hope remains that more employers eventually participate, particularly if the contributions represent genuinely additional compensation rather than money diverted from existing retirement benefits.
But don’t confuse a generous legal allowance with a widely available workplace benefit.
The government can create tax incentives. It can’t make employers spend money they don’t believe produces enough value.
With 72% of PSCA survey respondents showing no interest, Trump Account contributions have a substantial adoption problem.
The bigger concern is that the children who benefit most will be those whose families already have the financial resources and employer benefits needed to save consistently. The $2,500 contribution has genuine potential.
Getting employers to offer it may prove considerably harder than creating the tax break.