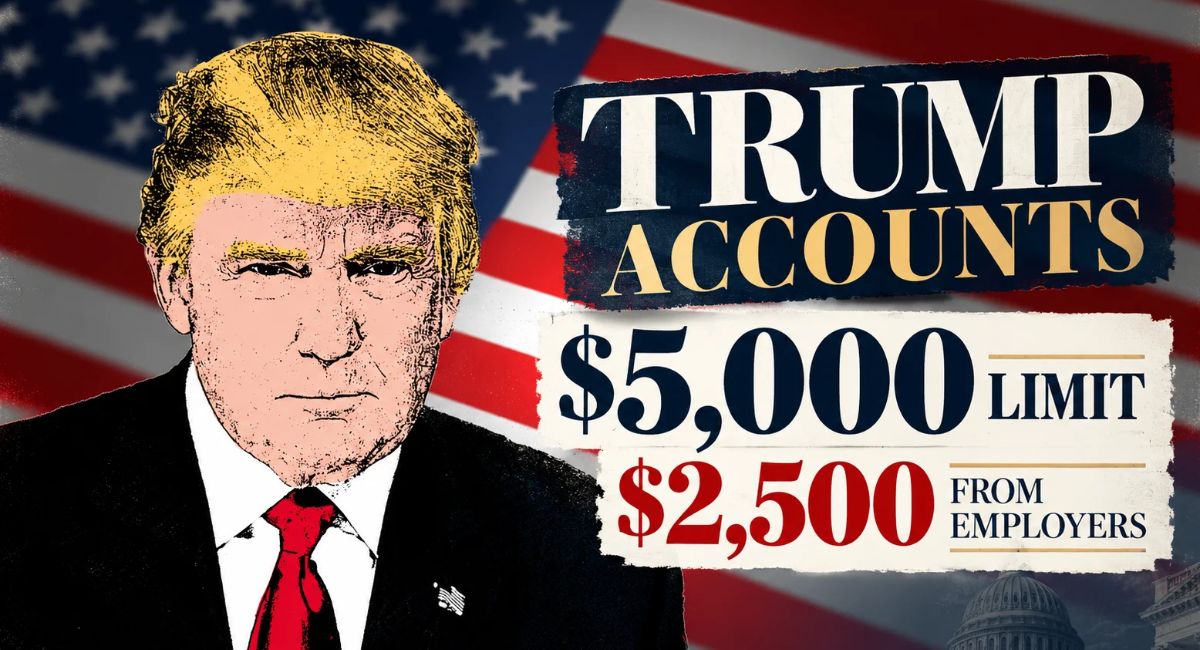
A child’s Trump Account can receive up to $5,000 in regular contributions in 2026. An employer can provide as much as $2,500 of that amount without adding it to the employee’s taxable income.
Those numbers sound straightforward. The relationship between them is where things get interesting.
The employer’s $2,500 allowance is not additional money on top of the $5,000 annual limit. It counts toward that limit. Meanwhile, some government and nonprofit contributions fall outside the cap entirely.
That creates several possible funding combinations, depending on the child’s eligibility, family contributions, and workplace benefits.
The employer provision deserves particular attention. It could become a meaningful new employee benefit, but the amount companies are legally permitted to contribute and the amount they actually offer are two different things. Here’s how the rules work in 2026.
The 2026 Trump Account Contribution Limit Is $5,000
Under the IRS contribution rules, a Trump Account can receive up to $5,000 in combined regular contributions during 2026.
That includes money contributed by parents, grandparents, other individuals, and employers.
The limit applies to each child’s account, not separately to every person contributing.
What happens when several people contribute to the same child’s account? In the video below, financial coach Karma Senge explains how parents, grandparents, and employers share the $5,000 annual contribution limit, using a simple funding example.
For example, if grandparents deposit $2,000 and parents contribute another $2,000, only $1,000 remains available under the regular annual limit.
Employer contributions use that same remaining space. The $5,000 limit also applies in 2027. Inflation adjustments begin after 2027, meaning the maximum can increase in future years.
Importantly, children do not need earned income to receive contributions during the account’s special growth period. That’s a significant difference from ordinary IRA contribution rules.
How Different Contributions Fit Together
Understanding who can contribute to a Trump Account is just as important as knowing the annual limit. In the video below, Wealth and Estate Law Group explains how contributions from family members and employers fit into the rules, including which payments count toward the $5,000 cap.
Consider these hypothetical 2026 funding scenarios:
| Contribution source | Scenario A | Scenario B | Scenario C |
|---|---|---|---|
| Employer | $0 | $2,500 | $1,500 |
| Parents and relatives | $5,000 | $2,500 | $3,500 |
| Total regular contributions | $5,000 | $5,000 | $5,000 |
| Federal seed, if eligible | $1,000 | $1,000 | $1,000 |
| Total deposited | $6,000 | $6,000 | $6,000 |
The table illustrates something worth remembering: a child eligible for the federal $1,000 contribution can receive $6,000 in 2026 without violating the $5,000 regular contribution limit.
Certain qualifying government and nonprofit contributions can increase that total further.
Employers Can Contribute $2,500, but It’s Per Employee
The employer rule comes from Section 128 of the Internal Revenue Code.
Under the IRS employer contribution guidance, employers can contribute up to $2,500 annually through qualifying Trump Account contribution programs, with that amount excluded from the employee’s gross income.
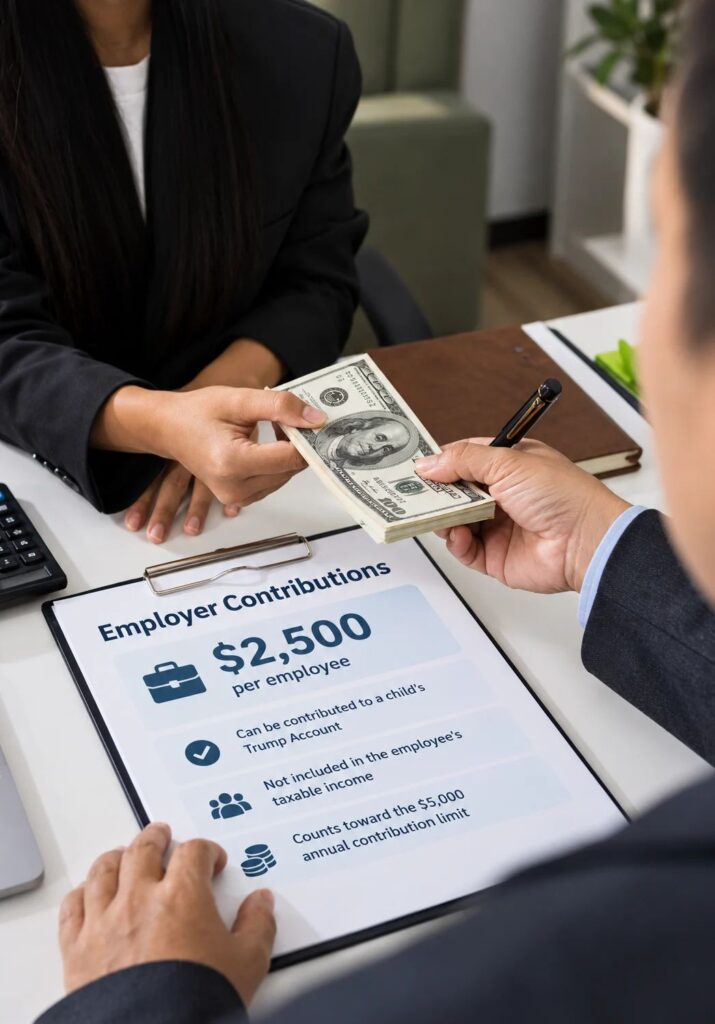
There’s an important limitation. The $2,500 exclusion applies per employee, not per child.
An employee with three eligible children does not automatically qualify for $7,500 in tax-free employer contributions.
Instead, the employee has one $2,500 aggregate annual allowance that can be divided among eligible dependents. Two working parents create a different possibility.
If both parents qualify under separate employer programs, each could receive $2,500 in contributions for the same dependent child. That could fill the child’s entire $5,000 regular annual allowance.
However, working multiple jobs does not double an individual employee’s tax-free employer limit.
It is probable that these distinctions will become increasingly important as employers begin incorporating the accounts into benefits packages.
Employers Must Establish a Qualifying Program
Employers cannot simply label any payment a tax-free Trump Account benefit.
The IRS’s August 2026 proposed regulations describe requirements for workplace programs, including a separate written plan, eligibility rules, and nondiscrimination protections.
Employers generally must avoid designing programs that unfairly favor highly compensated employees. The rules also contemplate contributions through Section 125 cafeteria plans.
This introduces an interesting distinction between employer-funded benefits and employee-funded savings.
An employer might contribute additional company money to a child’s account. Alternatively, a qualifying program could allow employees to redirect some of their own compensation into a dependent’s account on a pretax basis.
Those are economically different arrangements. One increases the employee’s total compensation. The other changes how existing compensation is received and taxed. Both can be valuable, but I wouldn’t describe them as equivalent.
And neither arrangement is mandatory. An employer’s ability to contribute $2,500 does not mean employees are entitled to receive it.
The Federal $1,000 Contribution Doesn’t Count Toward the Limit
The federal government’s one-time $1,000 contribution is separate from the regular annual cap.
Children born between January 1, 2025, and December 31, 2028, can qualify if they satisfy the program’s requirements, including U.S. citizenship and a valid Social Security number.
The pilot contribution must be requested through the applicable election process. Having an account alone should not be confused with securing the federal deposit.
Other children may qualify for Trump Accounts without qualifying for the initial $1,000.
The federal $1,000 contribution is only one part of the Trump Account program. In the video below, EisnerAmper’s Sarah E. Adkisson explains who may qualify, how the accounts work, and what families should know about contributions and investment rules.
We previously examined what a $1,000 Trump Account could become over several decades.
The main takeaway remains the same: the government contribution provides a starting point, but additional savings and investment performance will largely determine the eventual balance.
A $1,000 deposit is useful. A sustained habit of investing can be much more powerful.
Tax-Free Employer Contributions Aren’t Tax-Free Forever
There’s another distinction I think families should understand before getting excited about the tax benefits.
Qualifying employer contributions are excluded from the employee’s income when made. But that doesn’t mean the money will never be taxed.
Trump Accounts generally receive tax-deferred investment treatment. Employer contributions and the federal seed do not create tax basis, so they are generally taxable when eventually distributed.
Personal contributions are different. Parents and other individuals generally do not receive an immediate federal income-tax deduction, but those contributions create basis that can help prevent the original contributed amounts from being taxed again.
After the account’s special childhood growth period ends, traditional IRA rules generally apply, including potential taxes and early-withdrawal penalties.
That makes Trump Accounts quite different from 529 education plans, where qualified education withdrawals can generally be federally tax-free.
You shouldn’t automatically prioritize a Trump Account over a 529 for a family specifically saving for college.
The better choice depends on the purpose of the money and the available tax benefits.
What Families Should Know Before 2026 Ends
Trump Accounts began accepting contributions on July 4, 2026, following the Treasury Department’s official launch.
The full $5,000 regular contribution allowance applies for 2026 despite the midyear start.
Unlike ordinary IRA contributions, Trump Account deposits cannot be designated retroactively for a previous tax year. Contributions made in 2027 count toward 2027, not 2026.
One practical complication remains: the official Trump Accounts platform’s tax information FAQ still describes employer contributions as a forthcoming feature as of October 2026.
That means employers and families should verify operational availability rather than assume every legally permitted contribution method is already functioning.
For families considering deposits before year-end, tracking contributions from different sources is essential.
The Bigger Question Is Who Can Actually Afford to Contribute
The basic idea of giving children more years to participate in investment markets is good.
But contribution limits tell us how much someone can invest, not how much they realistically will.
For a financially comfortable household, contributing $5,000 annually might be manageable.
For a family struggling with rent, groceries, childcare, and debt, the same amount could be entirely unrealistic.
Our recent examination of Americans borrowing from their 401(k) accounts illustrates a broader problem: households can have long-term investments while still facing immediate financial pressure.
That’s why we see genuine employer-funded Trump Account contributions as potentially more consequential than the contribution ceiling itself.
A company adding $1,000 of its own money for an employee’s child provides a benefit that doesn’t require the family to sacrifice another $1,000 from its budget.
A payroll deduction program offers flexibility, but it doesn’t solve the affordability problem.
The Bottom Line
For 2026, the numbers are clear: $5,000 in regular annual contributions per child, including up to $2,500 in qualifying tax-free employer contributions per employee. The federal $1,000 seed and certain qualified general contributions are separate.
The rules are relatively generous for a new investment program. What’s more interesting is how much money will actually reach these accounts.
If employers embrace genuine additional contributions, Trump Accounts could become a meaningful new form of family compensation.
If most families are left to fund them entirely from their existing paychecks, the largest balances may accumulate where financial resources were already plentiful.
The contribution ceiling establishes the opportunity. Who can afford to reach it will determine much of the outcome.