America added more than 440,000 new dollar millionaires in 2025. Divide that across the calendar, and you get more than 1,200 people crossing the $1 million mark every day.
That is the headline number from the UBS Global Wealth Report 2026, and it is a big one. The United States accounted for almost half of the world’s newly created millionaires last year. More than 23.6 million U.S. adults now qualify as dollar millionaires, representing over 40% of the 57.5 million millionaires across the markets UBS tracks.
We read the 1,200-a-day figure mainly as a story about asset ownership. A strong stock market lifted retirement accounts, brokerage portfolios, employee stock holdings and business values. Housing added another push.
People already sitting at $900,000 or $950,000 in net worth did not need a lottery ticket. They needed their existing assets to appreciate enough to carry them over the line.
That distinction matters because “millionaire” sounds considerably more dramatic than the underlying math.
What UBS Means by a Millionaire
UBS is measuring wealth, not annual income.
Its methodology defines net worth as financial assets plus real assets, principally housing, minus debts. Private pension fund assets count as wealth, while state pension entitlements and future earning power do not. UBS calculates its figures around the adult population and uses year-end asset values.
A person counted as a new millionaire therefore did not need to earn $1 million during 2025. Their estimated net wealth needed to finish the year above $1 million.
That wealth can sit in a home, a 401(k), an IRA, taxable investments, business equity and cash, with mortgages and other debts deducted from the total. UBS makes the liquidity distinction explicitly: being a dollar millionaire does not mean having $1 million sitting in a bank or investment account.
That is the first useful filter to apply to the headline. Millionaire status in a wealth report is a balance-sheet measurement. It tells us much more about ownership than spending power.
2025 Was a Very Good Year to Own Assets
The market backdrop explains a large part of the increase.
The S&P 500 delivered a 17.88% total return in 2025, according to S&P Dow Jones Indices. That followed total returns of 25.02% in 2024 and 26.29% in 2023. Three strong years of compounding can move a portfolio a long way without spectacular new contributions.
Take a $700,000 stock portfolio. A 17.88% return adds roughly $125,000 before taxes, fees or withdrawals. For an investor whose home equity and other assets already put net worth close to seven figures, a year like 2025 can finish the job.
Federal Reserve data tells the same broader story. The Fed’s latest figures show household and nonprofit net worth increased by about $13.6 trillion during 2025. Financial-market gains supplied a large part of that increase, according to the Federal Reserve’s wealth data.
Housing helped too, although its national increase was far less dramatic. The Federal Housing Finance Agency reported that U.S. house prices rose 1.8% between the fourth quarter of 2024 and the fourth quarter of 2025.
The same effect is visible in workplace retirement plans. By the second quarter of 2026, 769,000 Fidelity 401(k) accounts had reached $1 million, demonstrating how market gains can move existing investors across major wealth milestones.
Here are the numbers we would like you to keep in view:
| Measure | 2025 figure | What it tells us |
|---|---|---|
| New U.S. dollar millionaires | 441,078 | More than 1,200 crossed the threshold daily |
| U.S. millionaire population | More than 23.6 million | Over 40% of the global total tracked by UBS |
| U.S. average wealth per adult | $696,277 | America has an enormous asset base |
| U.S. median wealth per adult | $68,998 | Wealth is distributed very unevenly |
| S&P 500 total return | 17.88% | Public markets gave asset owners a major lift |
| U.S. home-price growth | 1.8% | Housing provided a smaller nationwide tailwind |
The table also explains why resisting reading the 1,200 figure as evidence that 2025 suddenly transformed hundreds of thousands of ordinary incomes. Asset prices moved. People near the threshold moved with them.
The Average American and the Median American Live in Different Wealth Statistics
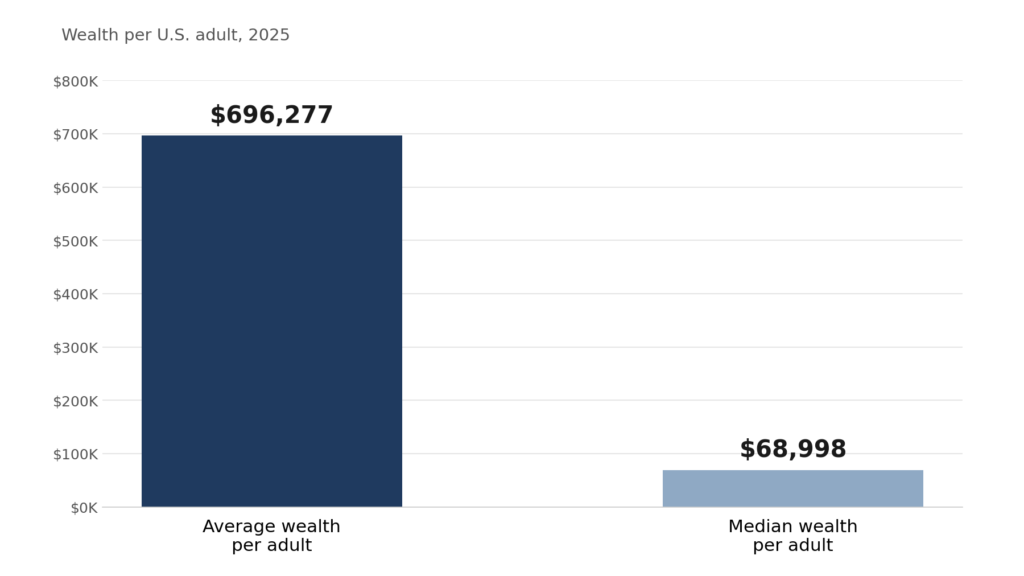
The most revealing numbers in the UBS report are not the millionaire count.
UBS estimates average wealth per U.S. adult at $696,277. Median wealth is just $68,998. The United States ranks second among the markets UBS tracks by average wealth per adult and 28th by median wealth.
That gap is enormous. Average wealth is more than ten times the median because a large share of American wealth sits near the top of the distribution.
Put one billionaire into a room, and the average wealth of everyone in the room jumps. The median barely notices.
Federal Reserve data makes the concentration visible. Using its fourth-quarter 2025 wealth figures, the top 10% held about $118.7 trillion of the roughly $174 trillion allocated across its wealth groups.
That works out to around 68% of the total. The bottom 50% held about $4.3 trillion, or roughly 2.5%, based on the Fed’s distributional wealth statistics.
America can therefore create 441,078 new millionaires in a year while millions of households remain nowhere near that threshold. Asset ownership is highly concentrated, so large market gains naturally produce large wealth gains near the top.
The 1,200-a-day figure describes movement among people already relatively high on the balance-sheet ladder. It does not describe the financial position of the typical American.
America Has a Powerful Millionaire-Making Machine
There is still something significant in the U.S. lead.
The United States now holds 35.7% of the personal wealth found across the 56 markets in UBS’s sample. The U.S. and Greater China together account for more than half. Average American wealth per adult is approaching $700,000.
American household balance sheets also contain enormous holdings of corporate equities, mutual funds, retirement assets, real estate and private businesses. When the value of those assets rises, existing owners participate automatically.
The scale of participation matters. The scale of ownership matters even more.
A 15% return on $50,000 creates $7,500. The same return on $900,000 creates $135,000. Same percentage. Very different movement in net worth.
Federal Reserve data shows just how concentrated financial assets are. In early 2026, the wealthiest groups owned the overwhelming majority of corporate equities and mutual fund shares, while the bottom half held only a small fraction of the total. The Fed’s wealth comparison data makes that ownership gap easy to see.
Money has always been good at making that particular point without much subtlety.
UBS also notes that millionaire populations depend on factors beyond economic size, including homeownership, private retirement savings, tax incentives for saving and investing, and what it calls the prevailing culture of investing.
That helps explain why the U.S. can keep producing new seven-figure balance sheets at such scale.
Crossing $1 Million Is Less Glamorous Than It Used to Be
There is another force working quietly in the background. The millionaire threshold remains fixed at one million nominal dollars. Its purchasing power does not.
One million dollars still carries a psychological weight left over from an era when the sum represented far more spending power. Decades of inflation have changed what the label means in practical terms.
A $1 million net worth still places someone in a strong financial position relative to most Americans. It no longer implies the lifestyle that popular culture attached to “millionaire” several decades ago.
A valuable home plus decades of retirement investing can push a person’s balance sheet above $1 million without producing anything resembling yacht money.
UBS has previously referred to people in the $1 million to $5 million range as Everyday Millionaires, and its 2026 report says the vast majority of the world’s millionaires remain below $5 million in wealth. More than 50 million people across its sample sit in that broader everyday-millionaire group.
That distinction is very useful. A person worth $1.05 million and someone worth $100 million both satisfy the everyday definition of “millionaire.” Their financial lives have almost nothing in common.
A Millionaire Count Can Move Backward
The mechanism that pushes people across $1 million also works in reverse.
Net worth follows asset values. Stocks fall. Business valuations get cut. Property prices decline. Debt stays on the other side of the balance sheet.
Someone finishing the year with $1.03 million in net wealth can drop below the threshold after an ordinary market correction. Millionaire status in an annual wealth study does not come with lifetime membership.
UBS also cautions that it revisits its data and methodology when estimating millionaire populations, meaning current and historical counts are not always directly comparable across editions.
Treat the annual millionaire count as an indicator of where wealth is moving, rather than a permanent headcount of people who have “made it.”
Income creates the capacity to save. Ownership gives those savings exposure to asset growth. Market prices determine what that ownership is worth at a specific point in time.
What the 1,200-a-Day Number Really Says
The headline holds up. America created more than 1,200 new dollar millionaires per day in 2025, with UBS putting the annual increase at 441,078 people.
The more useful story sits underneath that figure.
America entered 2025 with a huge population already close to the millionaire threshold. Another strong year for equities pushed hundreds of thousands across it. Home prices contributed additional gains. Long-built retirement accounts, business equity, and accumulated savings supplied the base.
The gap between $696,277 in average wealth and $68,998 in median wealth tells us just as much about the country. America is extraordinarily wealthy in aggregate. Ownership of that wealth remains heavily concentrated.
That is the number worth remembering. Wealth creation moves through the economy according to who owns the assets.
A salary pays expenses and provides money to save. A balance sheet determines whether a strong year in markets changes your wealth by $5,000, $50,000, or $500,000.
In 2025, American asset owners got another strong year. More than 1,200 people a day crossed one of finance’s favorite round numbers along the way.